Measure incremental revenue from ecommerce promotions by subtracting the sales you would have earned without the offer from actual net sales. A randomized holdout gives the strongest comparison; a historical baseline provides a less certain estimate.
Your campaign dashboard can’t make that distinction alone, because attributed revenue includes customers who would have purchased anyway. Start with a defensible estimate of sales without the offer, then account for discounts, displaced purchases, and costs before calling the promotion successful.
Key Takeaways
- Measure additional net revenue, rather than total sales or coupon redemptions.
- Use randomized holdouts where feasible, and label historical comparisons as estimates.
- Judge success after discounts, returns, cannibalisation, and the post-promotion period, with contribution profit as a financial guardrail.
Separate Incremental Revenue From Campaign Revenue
Incremental sales are purchases an offer, discount, or campaign genuinely caused, measured against what would have happened without it.
Total promotional revenue includes every purchase during the campaign. Attributed revenue assigns purchase credit under a reporting rule, such as last-click attribution. Neither proves causality.
If a customer would have paid full price, discounting their purchase gives away margin without creating additional demand.
A randomized incrementality test estimates the missing outcome: what comparable customers would have done without the intervention.
Use net revenue after discounts, refunds, and cancellations consistently. Compare whole-store outcomes when a promotion can shift purchases between products or channels.
Choose a Defensible No-Promotion Baseline
Historical comparisons help smaller stores estimate lift, but they can’t separate every competing explanation.
Same period last year
Compare matching weekdays and equivalent trading events. This handles seasonality better than an ordinary previous-week comparison.
However, last year’s revenue doesn’t reflect current growth. Changes in customer numbers, prices, distribution, or stock availability can distort the result.
Adjust for an established growth trend where evidence supports it. Record the adjustment separately so finance can distinguish observed sales from assumptions.
Immediately preceding comparable weeks
Recent comparable weeks better reflect the store’s current growth level. However, they don’t automatically account for seasonality.
Exclude unusual trading conditions, including stockouts or unrelated promotions. Also match weekday patterns and account for changes in media spend.
For seasonal peaks, neither historical option provides a clean causal answer. Report a range under plausible baseline assumptions instead of presenting one estimate as certain.
Design a Promotion Test That Measures Causality
Randomize eligibility before exposure
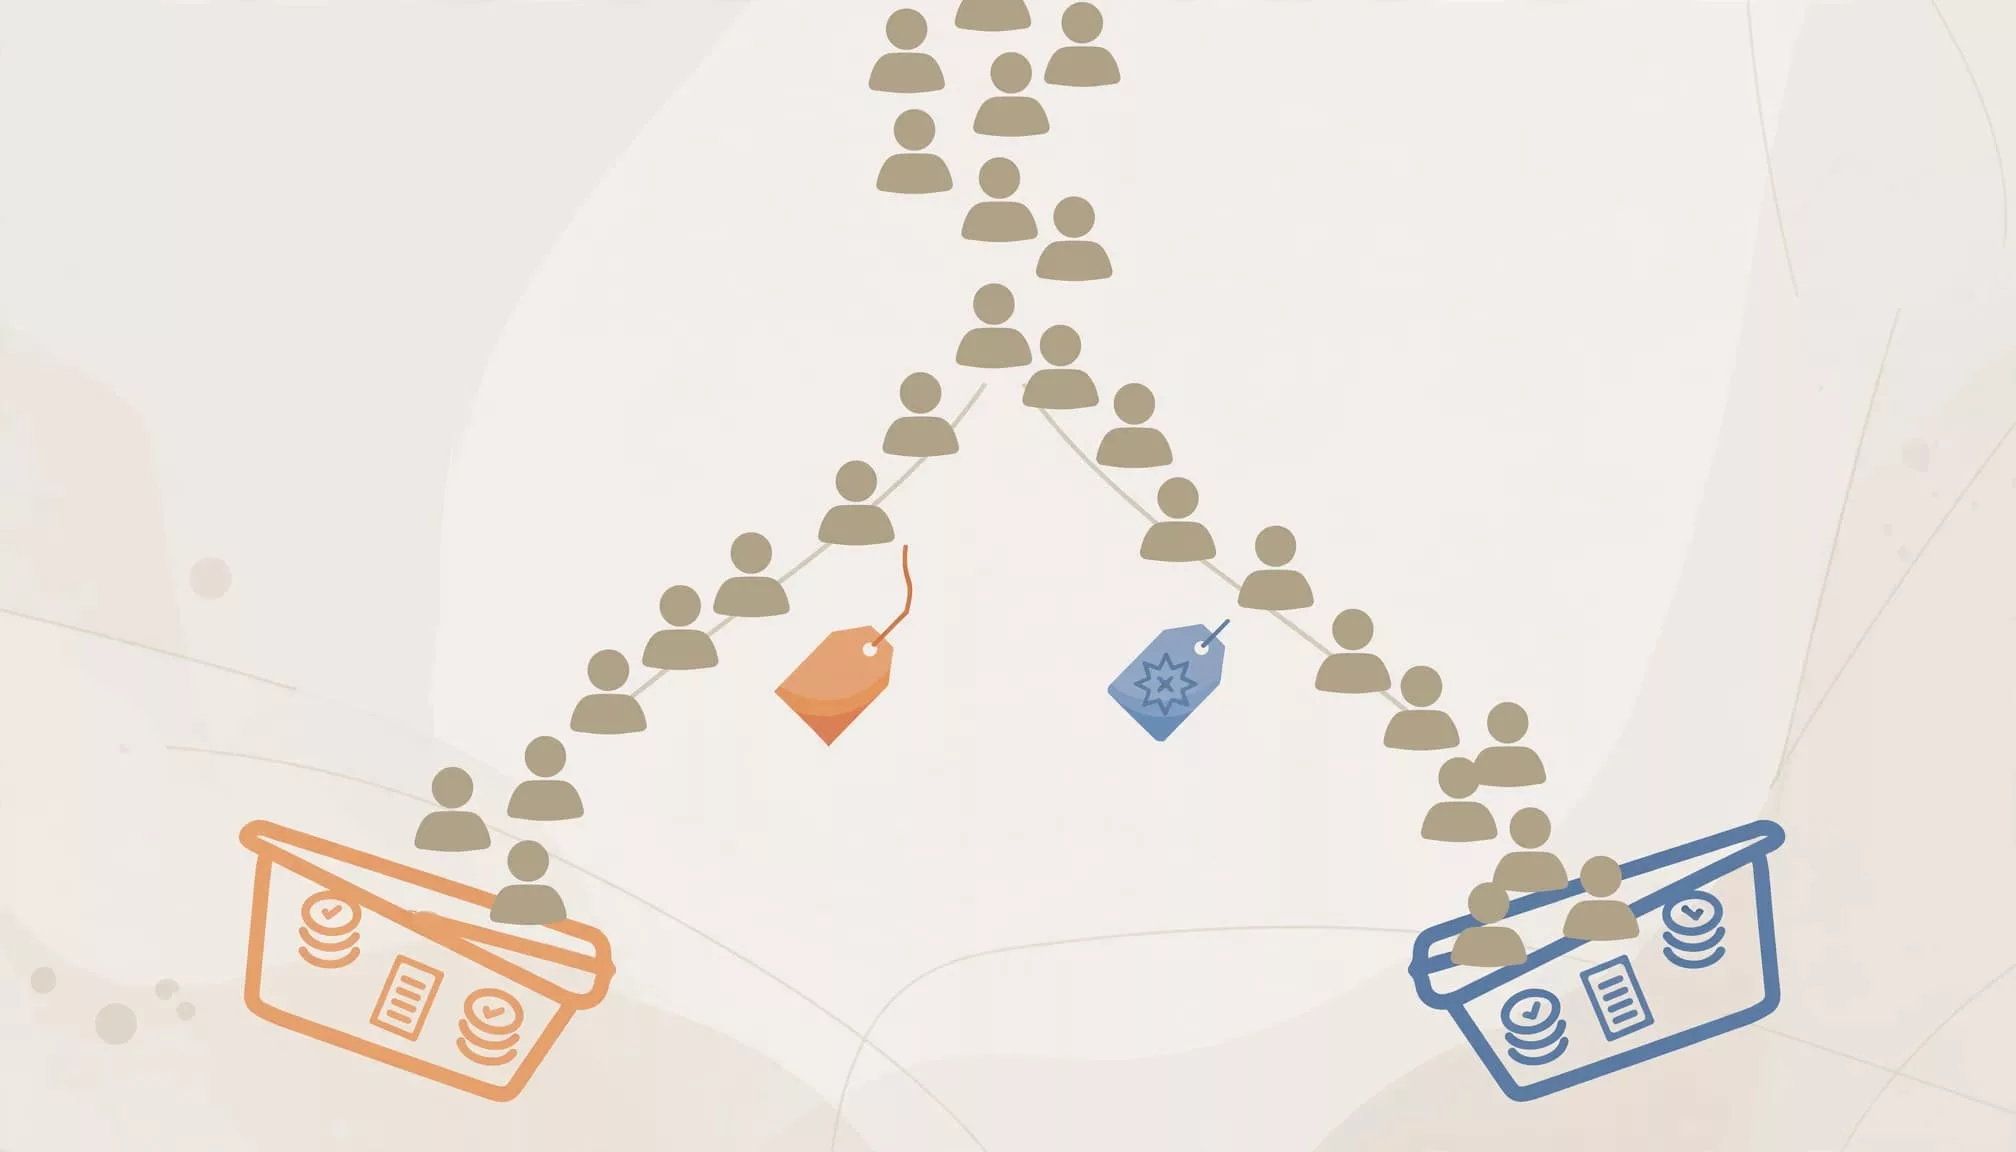
Randomly assign eligible customers to treatment and holdout before sending the offer. Keep each customer’s assignment consistent across visits and devices where identification allows. This is the strongest form of incrementality measurement because it estimates outcomes for comparable customers who don’t receive the offer.
For sales incentive programs, assign eligible customers to treatment or holdout before they receive the incentive.
The treatment receives the promotion; the holdout doesn’t. To isolate discount depth, keep messaging and timing equivalent. Otherwise, you’re testing the combined message-and-offer package.
Measure everyone assigned, including non-openers and non-redeemers. Comparing redeemers with non-redeemers creates selection bias because those groups already differ in purchase intent.
Google’s Conversion Lift documentation describes controlled experiments for measuring advertising-driven incremental conversions. A promotion holdout follows the same causal principle, although it tests a different intervention.
Predefine the decision rules
Choose the primary metric, minimum worthwhile lift, observation window, and acceptable financial downside before launch. Use net revenue per eligible customer when basket values vary.
Plan traffic requirements with our A/B test sample-size guide. Small samples and early stopping can turn ordinary variation into an apparent win.
Also monitor control-group offer leakage. If customers share codes, the measured treatment difference may shrink. Where customer-level holdouts are impractical, matched geographic tests offer another option, though regional differences require careful adjustment.
Calculate Incremental Revenue and Sales Lift
Compare revenue per eligible customer
Use this formula when groups differ in size:
Incremental revenue = (treatment net revenue per eligible customer minus control net revenue per eligible customer) x treatment customers
For an equal-sized worked example, assume one unit per order and no refunds yet. Both groups contain 2,000 eligible customers.
| Metric | Control | Promotion |
|---|---|---|
| Conversion rate | 5% | 7.5% |
| Orders | 100 | 150 |
| Price paid | $100 | $80 |
| Revenue | $10,000 | $12,000 |
| Gross profit at $60 unit cost | $4,000 | $3,000 |
Incremental revenue is $12,000 minus $10,000 = $2,000, a 20% revenue lift.
The promotion generated $12,000 in total revenue, but only $2,000 above the control group’s $10,000 in expected sales. The remaining $10,000 isn’t incremental.
Keep conversion lift separate
The conversion-based formula is:
Incremental Sales Lift (%) = [(TGR – CGR) / CGR] x 100
TGR means test group conversion rate; CGR means control group conversion rate.
With 7.5% treatment conversion and 5% control conversion, the calculation is:
[(7.5% – 5%) / 5%] x 100 = 50%
That’s a 50% relative conversion lift, or 2.5 percentage points. Revenue increased only 20% because the offer lowered the selling price.
Report confidence intervals alongside experimental estimates. Neither percentage alone establishes that the result will repeat.
Check Margin, Discount Cost, and Returns
The worked example loses $1,000 in gross profit despite producing additional revenue.
At a $100 selling price and $60 product cost, gross margin is 40%. A 20% discount reduces unit gross profit from $40 to $20. You therefore need twice the units to preserve gross profit, assuming unchanged unit costs.
A 30% volume lift produces only $2,600 gross profit on 130 units, compared with $4,000 on 100 full-price units.
The discount also applies to customers who would have bought at full price, so it reduces profit without creating additional demand. Extra orders must cover that lost margin before the promotion creates additional profit.
Next, calculate contribution after payment fees, fulfillment, shipping subsidies, and return-related costs. Subtract incremental campaign and implementation costs separately.
Don’t subtract the discount twice: revenue recorded at $80 already includes the price reduction.
Finally, compare refunds and returns after equivalent elapsed time for both groups. Our profit-focused testing guardrails help connect conversion results with these downstream outcomes.
Adjust for Cannibalisation and Pull-Forward
Measure displaced purchases across the business
Product cannibalisation occurs when a discounted line takes sales from an undiscounted alternative. The promoted SKU can surge while category revenue barely changes and margin falls.
Channel cannibalisation happens when customers switch purchase routes. Email may claim revenue that would otherwise have arrived through direct traffic or branded search.
Also separate new and returning customers. A broad acquisition offer may subsidize established buyers, so higher redemption doesn’t necessarily mean additional customer acquisition.
Measure customer-level, category, and store-wide outcomes alongside campaign totals.
Extend measurement beyond the promotion
Pull-forward occurs when someone buys now instead of next month. Strong promotional sales can therefore produce weak subsequent weeks.
Continue observing through a relevant repurchase cycle. Using the worked example, a $1,000 treatment shortfall afterward would reduce the original $2,000 revenue lift to $1,000 across both periods.
Include this follow-up period for both groups. Otherwise, you’re measuring purchase timing rather than sustained additional demand.
Track Customer Quality Alongside Revenue Lift
Use basket and retention metrics diagnostically
Average order value shows whether baskets became larger or merely cheaper. Pair it with units per order and contribution dollars.
Compare repeat purchase rates for discounted and undiscounted first orders over identical windows. For a loyalty program offer, a member holdout can show whether the incentive caused another purchase. Acquisition holdouts provide stronger evidence of whether an offer reached customers who otherwise wouldn’t have purchased.
Also monitor support contacts, chargebacks, and unsubscribe rates. More purchases accompanied by confusion or complaints may weaken future customer value.
Acquisition is often cited as costing five to 25 times more than retention. Harvard Business Review’s customer retention analysis cites Bain research linking a 5% retention increase with profit increases of 25% to 95%. These broad findings aren’t guaranteed promotion outcomes.
Treat ROAS as supporting evidence
Incremental sales lift connects to conversion rate, return on ad spend (ROAS), and customer lifetime value. A successful campaign can improve all three, but discounts and lower-quality acquisitions can make them diverge.
Cost per click and cost per acquisition measure costs, not whether advertising caused incremental outcomes. Compare an ad campaign’s incremental contribution with its cost to assess incremental return on investment.
The retail media incrementality debate illustrates why attributed performance deserves scrutiny. In one case published by Incremental, top-keyword campaigns absorbed 93% of spending and generated about $1.20 incremental revenue per dollar. Long-tail keywords produced nearly twice the incremental revenue.
That case isn’t a universal budget rule. It shows why attributed ROAS can misvalue advertising inventory.
FAQ
What do incremental sales mean?
Incremental sales are additional purchases caused by an intervention, beyond purchases expected without it. Measure incremental units, orders, or revenue separately because discounts can make them move differently.
What does incremental growth mean?
Incremental growth is the increase above a credible estimate of what would have happened without the intervention. Ordinary year-over-year growth isn’t automatically incremental campaign growth because seasonality and existing business momentum also affect sales.
What does incremental annual revenue mean?
It’s additional revenue attributable to an intervention across a year. Don’t automatically annualize a short promotion’s lift: repeat exposure, seasonality, and purchase pull-forward can change the result.
What does incremental profit mean?
Incremental profit is the difference between profit with the promotion and estimated profit without it. Include lost margin on baseline purchases, variable costs, returns, and incremental campaign expenses.
Make the Decision on Additional Profit
A promotion earns its place when it produces incremental revenue growth at acceptable economics. Total campaign revenue and attribution reports can’t establish that alone.
Estimate what sales would have been without the promotion, measure equivalent customer outcomes, and include the post-promotion period. Then judge the result on incremental contribution, so a busier store doesn’t conceal a less profitable business.