A cash conversion cycle calculator measures the days between paying for inventory and collecting cash from customers. Calculate it by adding inventory days and collection days, then subtracting supplier payment days.
For an ecommerce store, cash timing explains why rising sales can coexist with a tight bank balance. Start with consistent accounting inputs, then separate customer payment delays from payment-provider settlement delays.
Key Takeaways
- Calculate CCC as days inventory outstanding plus days sales outstanding minus days payable outstanding.
- Use matching reporting periods and average balances so seasonal purchases don’t distort the result.
- Improve inventory timing, collections, and supplier terms without sacrificing product availability or contribution margin.
How the Cash Conversion Cycle Calculator Works
Start with the CCC formula
The Corporate Finance Institute’s CCC explanation breaks the cycle into three components. Use a CCC calculator to apply the formula to your business figures:
CCC = DIO + DSO – DPO
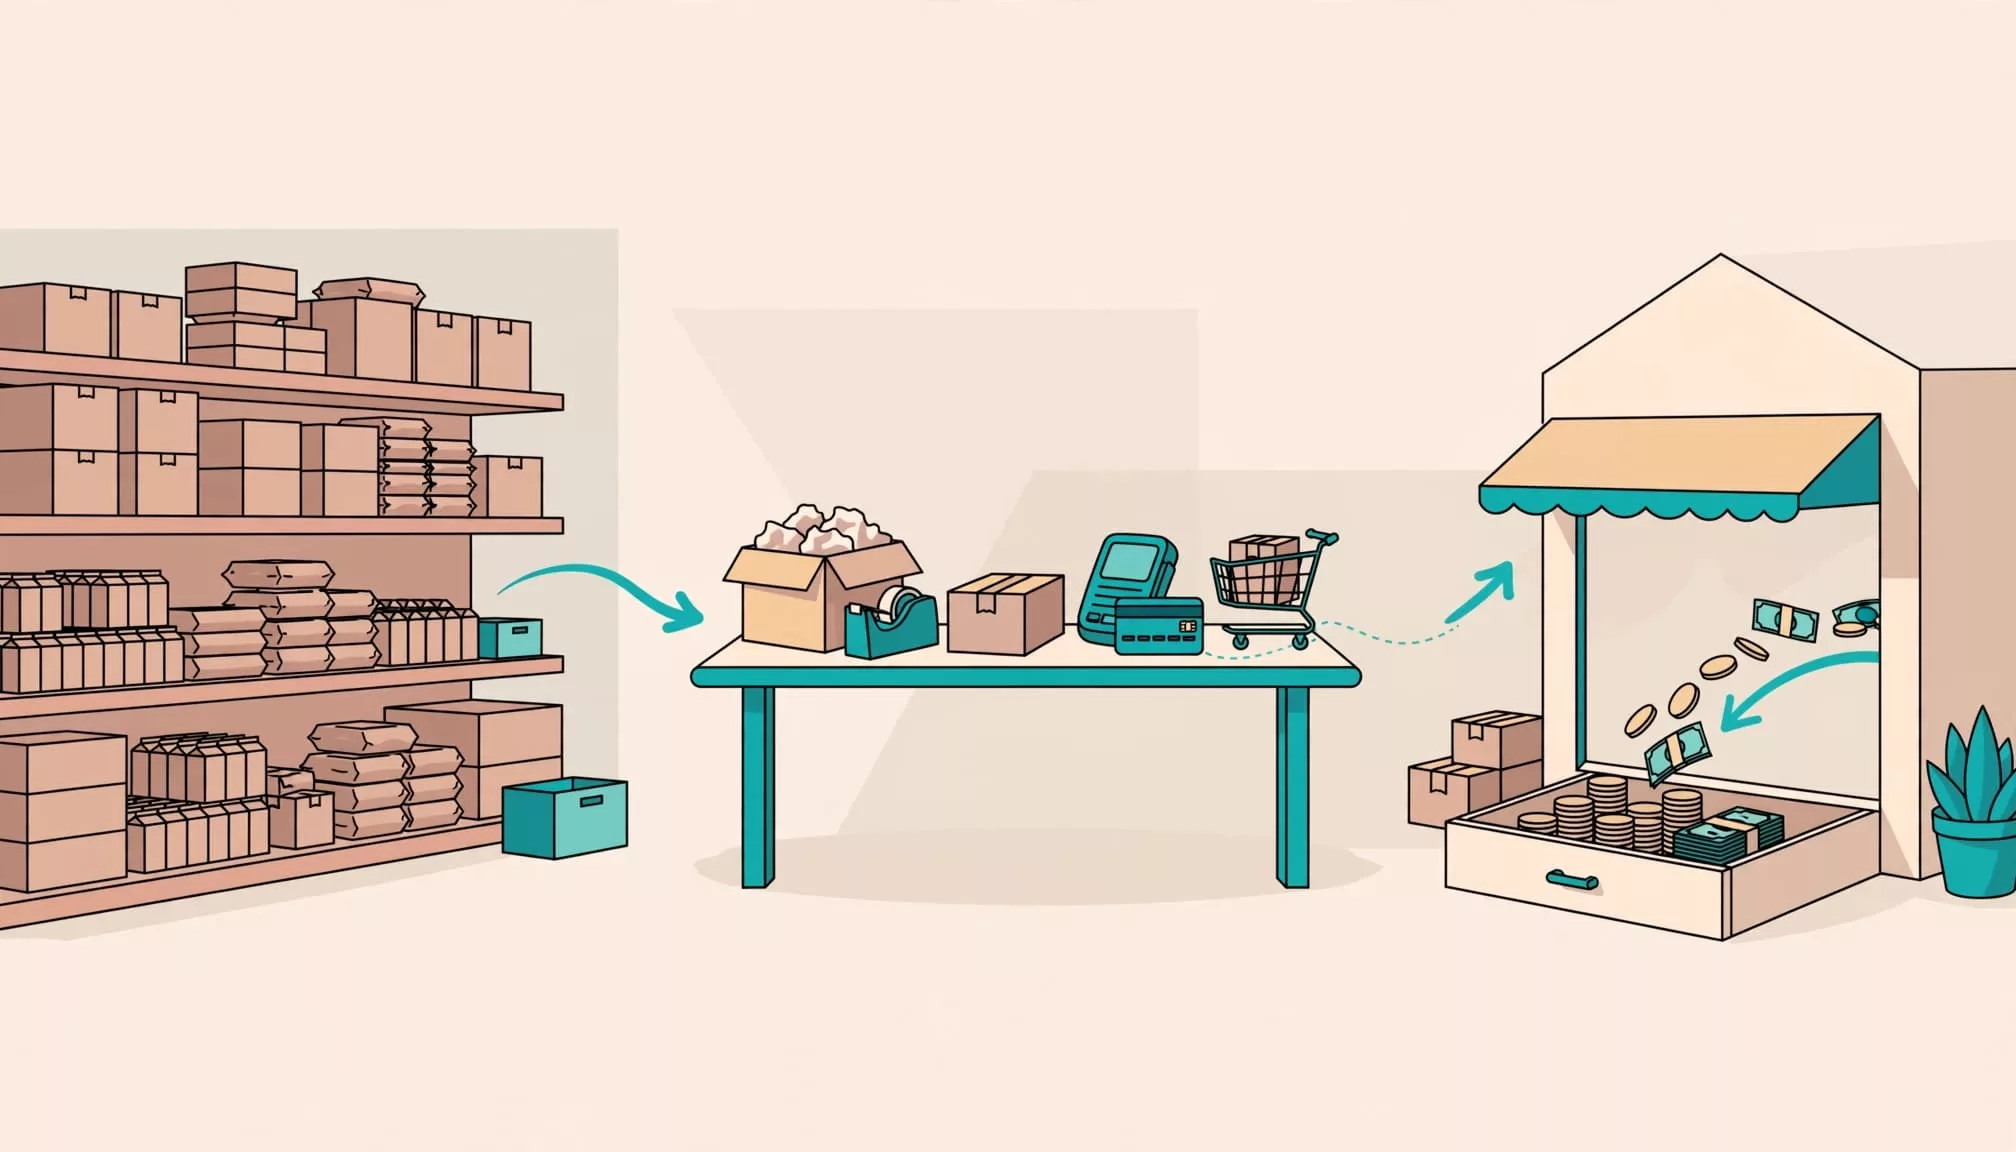
Days inventory outstanding (DIO) measures how long inventory sits before selling. Days sales outstanding measures customer collection time. Days payable outstanding (DPO) measures how long the business takes to pay suppliers.
Adding DIO and DSO gives the operating cycle. Subtracting DPO accounts for supplier credit that finances part of that period.
Calculate each component
For a trailing 12-month calculation, use these formulas.
| Component | Annual calculation |
|---|---|
| DIO | Average inventory / annual cost of goods sold x 365 |
| DSO | Average accounts receivable / annual revenue x 365 |
| DPO | Average trade accounts payable / annual cost of goods sold x 365 |
Using total revenue gives a blended customer collection time across cash and credit sales. For credit-customer collection analysis, use credit sales and the corresponding receivables instead. Keep this collection-time measure consistent between periods.
COGS is the cost of goods sold, not the retail value of products.
Find the Right Figures in Your Books
Match financial statements and average balances
Take annual revenue and COGS from the last 12 months of your profit and loss statement. Find inventory, balances due from customers, and trade accounts payable in your balance sheet or supporting inventory and aging reports.
JPMorgan’s component calculations also use average balances against annual activity. A simple average uses opening plus closing balances, divided by two. However, several month-end balances provide a steadier estimate for seasonal stores.
Value inventory at its accounting cost. Also, match supplier payables to the costs in your denominator rather than including unrelated liabilities such as taxes or loans.
Separate customer credit from processor settlement
An unpaid wholesale invoice and a captured card payment awaiting payout are different assets.
For Shopify Payments, PayPal, or marketplace sales, funds may sit in a clearing account rather than trade receivables. Track capture dates, payout dates, reserves, refunds, and bank arrival separately. Our Shopify payout reconciliation workflow helps connect those records.
If you include processor balances in an operational collection metric, label that adjustment. Don’t compare it directly with a trade-receivables-only DSO.
A customer can have paid while your store still can’t spend the money. Customer collection time and payout availability need separate visibility.
Worked Example: Calculate a 60-Day Cycle
For an ecommerce business with substantial invoiced sales, the calculation can use the following annual figures. All balance-sheet amounts are averages across the same reporting period.
| Input | Amount |
|---|---|
| Annual revenue | $1,460,000 |
| Annual COGS | $730,000 |
| Average inventory | $80,000 |
| Average accounts receivable | $200,000 |
| Average trade accounts payable | $60,000 |
Inventory days are $80,000 / $730,000 x 365 = 40 days.
Collection days are $200,000 / $1,460,000 x 365 = 50 days.
Supplier payment days are $60,000 / $730,000 x 365 = 30 days.
Therefore, CCC = 40 + 50 – 30 = 60 days.
The business carries inventory for 40 days, then waits another 50 days for collection on average. Supplier credit covers 30 days, leaving a 60-day funding gap.
That long DSO fits a receivables-heavy operation. A store collecting payment at checkout would usually have much shorter customer collection time, although settlement delays can still restrict available cash.
Enter the same inputs into your cash conversion cycle calculator each month. Save the component results alongside the headline number so you can identify which part changed.
Interpret the Result Against Your Business Model
A longer cycle needs context
A positive CCC means the business generally pays suppliers before collecting the related customer cash. Longer cycles increase the period that working capital needs funding, but they don’t automatically indicate financial trouble.
A restaurant naturally tends toward a short cycle because stock moves quickly and customers pay promptly. A manufacturer offering 45-day customer terms may have a longer cycle that fits its commercial model.
The CFA Institute’s discussion of CCC connects these components to operating cash requirements. Compare your trend with similar seasons, product mixes, and payment terms before judging performance.
Competitor comparisons need matching definitions, too. A prepaid retail store and a wholesale-heavy seller won’t have comparable collection patterns.
A negative cycle means customers fund operations
A negative cash conversion cycle means customers pay before supplier bills become due. Supplier credit can fund working capital that might otherwise require bank financing, supporting liquidity and cash flow.
For example, fast inventory turnover combined with immediate customer payment can produce this result when suppliers offer longer terms.
However, a negative cycle doesn’t prove profitability or eliminate cash risk. Refunds, supplier deposits, or payment-provider reserves can still create pressure that the headline metric doesn’t fully describe.
Shorten the Cycle Without Damaging the Store

Reduce inventory days through better replenishment
To shorten the cash conversion cycle, focus first on the component tying up the most cash.
Use inventory management reviews to assess slow-moving SKUs, supplier lead times, minimum order quantities, and purchasing frequency. Smaller, better-timed orders can release cash, although higher freight costs may offset some benefit.
Compare inventory turnover by SKU with lead times to distinguish slow sellers from stock held for planned seasonal demand.
First, improve ecommerce inventory accuracy. Incorrect stock records encourage unnecessary purchases and hide unavailable products.
Also, track deposits and inventory in transit. Cash committed before stock enters your inventory records can make the accounting cycle look shorter than your actual funding requirement.
Collect customer payments sooner
For invoiced orders, send accurate invoices promptly and make payment instructions clear to support receivables collection. Automated reminders can reduce avoidable collection delays.
Accounts receivable automation can schedule staged reminders and flag overdue balances for review while staff handle disputes.
Early-payment discounts or priority delivery can encourage faster payment, provided the margin and fulfillment costs justify them. Faster delivery also helps when contractual payment timing starts at delivery.
For checkout-paid orders, fix failed payments and unnecessary capture delays. Additional payment methods may improve completion, but compare their settlement timing, fees, and refund handling.
Use agreed supplier terms and automate administration
Pay suppliers on agreed terms rather than routinely paying early. Negotiate supplier payment terms before changing payment behavior; overdue bills can damage supply relationships.
Automated accounts receivable and payable software can reduce entry errors, missed reminders, and unnecessary early payments without replacing the entire workflow.
However, automation can’t make an unfavorable contract disappear. Due-date scheduling helps preserve cash only when the underlying terms support it.
Set a Target and Estimate the Cash Effect
Use working capital management to plan component-level improvements before setting a combined target. The figures below show cumulative changes from the worked example.
| Scenario | DIO | Customer collection days | DPO | CCC |
|---|---|---|---|---|
| Starting position | 40 | 50 | 30 | 60 |
| Reduce stock days | 30 | 50 | 30 | 50 |
| Also collect sooner | 30 | 45 | 30 | 45 |
| Also extend agreed terms | 30 | 45 | 35 | 40 |
The combined target reduces the cycle by 20 days. Assign an operational change and owner to each component.
As a planning shortcut, each day removed frees cash roughly equal to one day of cost of sales. Here, daily COGS is $730,000 / 365 = $2,000.
For a more accurate estimate, calculate each lever separately. One DIO or DPO day uses daily COGS, while one blended customer-collection day uses daily revenue, which is $4,000 here.
These changes release approximately $50,000: $20,000 from inventory, $20,000 from receivables, and $10,000 through additional supplier credit. This is a working-capital release, not extra profit.
Frequently Asked Questions
Can a service business use this calculator?
Yes. Enter zero for inventory when the business holds none. Receivables and payables become the main drivers.
However, use a cost denominator that matches the relevant supplier payables. If COGS is zero, don’t divide by zero; calculate the applicable components separately.
Can I calculate CCC quarterly?
Yes. Use the quarter’s revenue and COGS, average balances for that quarter, and its actual number of days.
Don’t combine quarterly sales with a 365-day multiplier. For seasonal ecommerce businesses, compare the same quarter across years alongside the trailing annual result.
Does a shorter cycle mean better profitability?
No. Heavy clearance discounts can move stock faster while reducing contribution. Likewise, expensive financing or payment fees can accelerate cash availability without improving order economics.
Our ecommerce contribution margin calculator separates timing from profitability. Evaluate changes after discounts, fulfillment, payment costs, and returns. Keep refund and cancellation definitions stable so reporting changes don’t create a false improvement.
Make Cash Timing a Monthly Operating Metric
Your cash conversion cycle is most useful when you can explain every change in inventory, collections, and supplier payments. A lower number helps only when the underlying operations remain healthy.
Build a consistent baseline, then choose a practical target for the component tying up the most cash. Pair cash timing with contribution margin so faster cash supports profitable orders.